America’s two largest home improvement retailers are finding growth online even as the housing market faces mounting pressure from expensive mortgages and weakening builder confidence. Third quarter 2026 results released on November 17 and 18 show that Lowe’s recorded a 17.4 percent increase in online sales, while Home Depot reported higher overall revenue and comparable sales. The contrast highlights a changing home improvement market in which customers increasingly value convenient ordering, flexible delivery and professional contractor services, even when high borrowing costs discourage major housing purchases. At the same time, a new industry report shows that US homebuilder confidence has fallen to its lowest level in more than 14 years.
Home Depot Reports 13 Percent Online Sales Growth
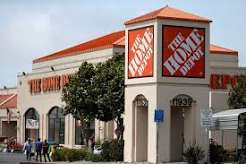
The Home Depot delivered a strong third quarter, reporting total revenue of $43.4 billion, an increase of 4.9 percent compared with the same period in 2025. Comparable sales increased 2.2 percent, while comparable sales in the United States also grew 2.2 percent.
One of the strongest areas of performance was the company’s digital business. Comparable sales through its online platforms increased approximately 13 percent year over year, marking the sixth consecutive quarter of double digit digital growth.
The retailer attributed this performance to continued investment in its digital shopping experience, including faster website performance, artificial intelligence powered search tools and more flexible fulfillment options. These improvements allow customers to identify products, compare available options and arrange deliveries with fewer obstacles.
Express Delivery has become another important part of the company’s strategy. Following its nationwide introduction, the service expanded to virtually all Home Depot locations, offering delivery on tens of thousands of products within two hours. The company reported that most express deliveries arrive in less than one hour.
More than half of Home Depot’s online orders are fulfilled through its physical stores, demonstrating how its retail locations function as distribution and fulfillment centers rather than simply traditional shopping destinations.
Professional Contractors Remain an Important Growth Driver
Home Depot also reported positive comparable sales across both professional and do it yourself customer groups, with professional customers outperforming individual consumers.
Contractors frequently purchase larger quantities of construction materials, electrical supplies, plumbing products and equipment. Their projects also require dependable delivery schedules because delays can affect labor costs and construction timelines.
Home Depot is responding through improved project management tools, digital material lists, delivery scheduling and business account services. These features allow contractors to manage purchasing and coordinate supplies for multiple projects.
The retailer also reported strength in categories including portable power equipment, pipe and fittings, water heaters, insulation, siding and hand tools. Big ticket transactions exceeding $1,000 increased 4.5 percent, reflecting continued demand for selected higher value products.
Lowe’s Records 17.4 Percent Growth in Online Sales
Lowe’s delivered an even stronger digital growth rate during its third quarter, reporting a 17.4 percent increase in online sales compared with the previous year. The performance marked its fifth consecutive quarter of double digit online growth and its third consecutive quarter above 15 percent.
The company’s total third quarter sales reached approximately $22.8 billion, compared with $20.8 billion in the corresponding period of 2025. This represented an increase of 9.3 percent. Comparable sales grew 1.8 percent, supported by online purchasing, professional customers and home services.
Lowe’s results demonstrate that digital demand is not limited to one major home improvement retailer. Customers are increasingly using online platforms to research products, arrange purchases and choose convenient collection or delivery options.
Chief Executive Officer Marvin Ellison credited the company’s continued growth to its broader Total Home strategy, which combines physical stores, digital shopping, professional services and home improvement solutions.
For customers, the appeal is straightforward. A homeowner planning a kitchen renovation or a contractor preparing for a busy workday can arrange purchases without spending unnecessary time visiting multiple stores. Flexible fulfillment also makes it easier to coordinate materials with project schedules.
Fulfillment Investments Support Continued Digital Expansion
Lowe’s has invested in improving the connection between its online operations and physical retail network. These investments provide customers with greater flexibility in how and when they receive their purchases.
The company’s digital strategy serves both do it yourself shoppers and professional contractors. Individual consumers may order appliances, tools and renovation supplies, while professional customers can use online services to manage purchasing for ongoing jobs.
This combination is commercially important because home improvement spending includes both large renovation projects and smaller maintenance requirements. Even when homeowners postpone expensive upgrades, they may still need replacement appliances, plumbing repairs, electrical components and essential maintenance supplies.
That recurring demand provides retailers with an opportunity to maintain sales even when the broader housing market becomes less active.
US Homebuilder Confidence Falls to Its Lowest Level Since 2012
The strong digital results from Home Depot and Lowe’s contrast with the growing difficulties facing residential construction businesses.
On November 17, the National Association of Home Builders reported that its Housing Market Index fell four points to 25 in November 2026. This represented the lowest reading since April 2012, placing builder confidence at a more than 14 year low.
The index measures how homebuilders view current sales conditions, expected sales over the next six months and traffic from prospective buyers. A reading above 50 indicates that more builders view market conditions positively than negatively. A reading of 25 therefore reflects substantial pessimism across the industry.
Higher mortgage rates, persistent inflation, expensive building materials and labor shortages are contributing to the downturn. Builders are also concerned about weaker consumer confidence and the financial pressure facing prospective homebuyers.
The November report revealed additional signs of stress:
- 46 percent of builders reported reducing home prices, the highest proportion in the post pandemic period.
- Average price reductions remained at 6 percent for the eighth consecutive month.
- 68 percent of builders offered sales incentives to attract potential buyers.
- Current sales conditions fell to 28, reflecting weaker assessments of the new home market.
- Prospective buyer traffic dropped to 16, its lowest level in 15 years outside the beginning of the pandemic.
These figures indicate that builders are increasingly relying on discounts and financial incentives to attract customers. Some are also reconsidering construction plans as weaker demand and higher operating expenses put pressure on profitability.
Mortgage Rates Continue to Pressure Homebuyers
High mortgage rates remain one of the most important challenges facing the American housing market. When borrowing becomes more expensive, households often find it harder to qualify for mortgages or afford the monthly payments associated with purchasing a new property.
During October, the average rate on a 30 year fixed mortgage reached approximately 7.40 percent at its midmonth peak, its highest level in three years. Although rates subsequently eased, they remained above 7 percent during the period covered by the November housing confidence report.
For a family considering a new home, the difference between a mortgage rate of 5 percent and one above 7 percent can significantly affect monthly expenses. Higher payments may force buyers to postpone purchases, select smaller properties or remain in their existing homes.
That decision creates a ripple effect throughout the housing industry. Fewer home purchases can reduce demand for new construction, appliances, renovation materials and related services.
Builders are attempting to respond through lower prices, mortgage rate incentives and other purchasing benefits. However, these measures cannot fully resolve the affordability problems created by elevated borrowing costs and rising construction expenses.
Why Home Improvement Retailers Can Grow During a Housing Slowdown
The contrasting performance of major home improvement retailers and residential builders reveals an important difference between buying a home and maintaining one.
When mortgage rates rise, some households delay moving or purchasing additional properties. However, they still need to maintain their existing homes. A leaking roof, broken water heater, damaged flooring or malfunctioning appliance cannot always wait for more favorable economic conditions.
Homeowners may also decide that renovating their current property is more affordable than purchasing another home. This can support demand for renovation materials, replacement appliances, plumbing supplies and home maintenance products.
Professional contractors provide another source of demand. Their businesses depend on repair work, maintenance contracts and renovation projects, not exclusively on new residential construction.
Consequently, the performance of Home Depot and Lowe’s suggests that essential home improvement spending remains relatively resilient, even as the housing market experiences weaker buyer confidence.
However, this does not mean the retailers are completely protected from an extended housing slowdown. Large renovation projects can also be postponed when households face financial uncertainty. The companies must therefore continue balancing professional demand, smaller household purchases and discretionary home improvement spending.
What the Results Mean for the Retail Industry
The latest earnings reports provide several important insights into the future of home improvement retail.
First, digital commerce is becoming an increasingly important source of revenue. Growth of 13 percent at Home Depot and 17.4 percent at Lowe’s suggests that customers are responding positively to improved online shopping experiences and flexible fulfillment arrangements.
Second, professional customers remain a valuable part of the business. Contractors often need reliable product availability, accurate delivery estimates and tools that help them manage complicated purchasing requirements. Retailers that provide these services can build stronger relationships with business customers.
Third, physical stores continue to play an essential role in digital retail. Both companies are using their existing store networks to support online orders, customer collection and product delivery. This interconnected approach allows retailers to serve customers through multiple purchasing channels.
Finally, the housing slowdown demonstrates why retailers need to maintain a broad customer base. Demand from contractors, homeowners and smaller maintenance projects can help offset weaker activity in new residential construction.
What Investors and Consumers Should Watch Next
Investors will be watching whether the two retailers can maintain their digital growth while protecting profit margins. Higher transportation expenses, labor costs, product prices and promotional activity could affect profitability even when sales continue increasing.
Home Depot has projected approximately 4.5 percent total sales growth for fiscal 2026, while expecting comparable sales to increase approximately 1.4 percent. Lowe’s has updated its full year sales outlook to approximately $92.5 billion.
For consumers, the most useful indicators will include delivery availability, product pricing, contractor services and promotional offers. Competitive pricing may provide opportunities for households planning necessary repairs, although major renovation decisions should still account for financing costs and available budgets.
Future mortgage rate movements will also matter. If borrowing costs decline, more prospective homebuyers could return to the market, potentially supporting new construction and additional spending on home improvement products.
Digital Retail Growth Offers a Bright Spot Amid Housing Market Uncertainty
The third quarter results from Home Depot and Lowe’s demonstrate that the American home improvement industry is experiencing two very different trends. Online shopping is growing rapidly, supported by better delivery services, improved digital tools and continued contractor demand. Meanwhile, residential builders are confronting weaker buyer traffic, expensive financing and declining confidence.
Home Depot’s 13 percent digital sales growth and Lowe’s 17.4 percent increase show that investment in online fulfillment is delivering meaningful commercial results. Their ability to connect digital platforms with physical stores is also changing how consumers and professional contractors purchase home improvement supplies.
Nevertheless, the housing market remains an important factor in the industry’s longer term outlook. Persistent mortgage costs and affordability challenges could eventually affect renovation spending and broader consumer demand.
For now, both retailers appear to be finding opportunities in a difficult economic environment. Their next challenge will be sustaining digital momentum while navigating a housing market that remains under significant pressure.
Investors and homeowners can follow upcoming company earnings and housing industry developments through Home Depot Investor Relations and the National Association of Home Builders.