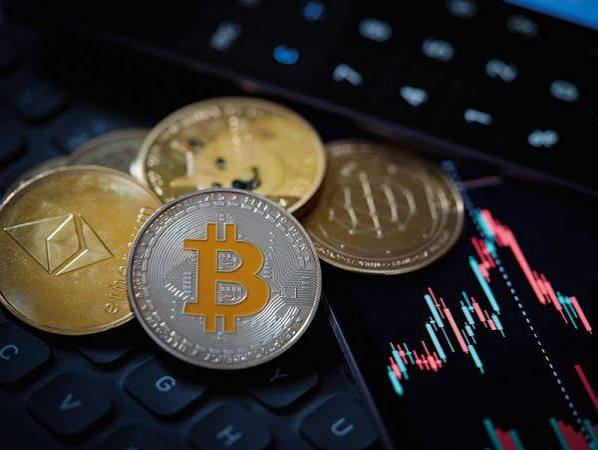
Bitcoin and several major altcoins reportedly found steadier footing on October 31, 2026, as renewed attention to digital asset regulation offered investors a more predictable picture of how institutions may hold cryptocurrencies and manage stablecoin reserves. For a market often driven by sudden shifts in confidence, clearer accounting and custody standards could help reduce uncertainty. However, regulatory progress does not remove the risks of crypto investing, and the reported stabilization should not be mistaken for a guaranteed market recovery.
For traders watching price screens late in the month, a period of relative calm can feel significant after weeks of sharp swings. Yet the reasons behind a market pause matter as much as the pause itself. In this case, regulatory developments may be contributing to improved confidence, particularly among banks, asset managers and other institutions considering digital asset services. Available official announcements confirm meaningful progress on stablecoin oversight and custody requirements, although they do not independently establish that Bitcoin and major altcoins all recorded a coordinated price recovery on October 31.
Why Regulatory Clarity Matters to Cryptocurrency Markets
Cryptocurrency prices respond to several forces at once. Investor demand, interest rate expectations, liquidity, technology developments and global economic conditions can all influence trading. Regulation adds another layer. When businesses cannot determine how digital assets should be held, reported or supervised, they may delay investments, restrict services or avoid entering the market altogether.
Institutional investors face particular challenges. A fund or bank handling cryptocurrency must consider who controls the private keys, how customer assets are protected, what happens if a custodian fails and how holdings appear in financial statements. These are not minor administrative questions. They affect risk management, audits, legal responsibility and the ability to explain financial exposure to clients and regulators.
Clearer standards can reduce some of that uncertainty. They do not make cryptocurrency safe or eliminate price volatility, but they can give established financial institutions a more consistent basis for evaluating digital asset services. That distinction helps explain why regulatory announcements can influence market sentiment even when they do not directly change the supply or demand for Bitcoin.
United States Stablecoin Rules Bring More Structure
One of the most consequential developments for the digital asset sector is the implementation of the Guiding and Establishing National Innovation for U.S. Stablecoins Act, commonly known as the GENIUS Act. The law establishes requirements for permitted payment stablecoin issuers, including reserve backing, redemption, risk management and supervision.
Under the statutory framework, payment stablecoin issuers must maintain identifiable reserves at a minimum one to one ratio against outstanding stablecoins. Permitted reserve assets include U.S. currency, certain deposits and other qualifying liquid assets. The purpose is to provide a stronger financial foundation for tokens designed to maintain a stable value against the U.S. dollar.
The Office of the Comptroller of the Currency added another important step on October 21, 2026, when it issued a final rule implementing parts of the GENIUS Act for entities under its jurisdiction. The rule addresses reserve assets, redemption, custody, audits, reporting and supervisory responsibilities. It is scheduled to take effect on January 18, 2027, meaning the announcement represents a move toward implementation rather than a set of requirements that are already fully in force.
For investors, the distinction is important. A stablecoin backed by identifiable reserves and subject to meaningful oversight may offer greater transparency than an arrangement with unclear reserve practices. However, reserve requirements cannot remove every risk. Investors still need to consider the issuer, the quality and availability of reserve assets, redemption conditions and the possibility of operational disruption.
Federal Reserve Proposals Address Reserve Quality and Custody
The Federal Reserve has also been working on the regulatory details. On September 24, 2026, the Board requested public comment on proposals covering payment stablecoin issuers supervised by the central bank under the GENIUS Act. The proposals address permissible reserve assets, capital requirements, risk management and rules for firms that safeguard assets backing stablecoins.
The Federal Reserve identified short term Treasury bills and certain other high quality liquid assets as examples of assets that could qualify for reserve backing. It also proposed standards intended to address credit and operational risks. Public consultation gives banks, issuers and other interested parties an opportunity to identify practical concerns before the rules are finalized.
These developments are relevant beyond stablecoin companies. Custody arrangements are a central part of institutional cryptocurrency activity. An institution may be willing to gain exposure to Bitcoin or another digital asset, but it needs confidence that assets are properly segregated, protected from unauthorized access and accounted for accurately. Strong custody standards can help address those concerns, although they cannot prevent every cyberattack, fraud or failure.
The Federal Reserve’s announcement is available through its stablecoin regulatory framework proposal. Its details also show why the regulatory picture is still developing: proposals, final rules and effective dates are separate stages of the process.
Global Regulation Is Moving Forward, but Not Under One Rulebook
The phrase global regulatory clarity can give the impression that governments have agreed on one common set of cryptocurrency rules. That is not yet the case. Countries and regional authorities continue to develop their own approaches, and requirements can differ in areas such as licensing, reserve composition, custody, disclosure and redemption rights.
The European Union, for example, applies its Markets in Crypto Assets Regulation, known as MiCA, to crypto asset issuers and service providers within its scope. On October 8, 2026, the European Securities and Markets Authority issued an opinion clarifying supervisory expectations for services involving stablecoins that do not comply with MiCA requirements. The guidance calls on authorized crypto service providers to stop offering covered services involving noncompliant tokens to European Union clients, subject to limited arrangements for dealing with existing exposures.
This illustrates a broader point: regulatory clarity does not always mean fewer restrictions. In some cases, clearer rules may limit which tokens exchanges can list or which services providers can offer. That can create short term disruption for businesses and customers, even as it makes the longer term compliance environment more predictable.
International coordination remains important because digital assets move across borders quickly. A stablecoin issuer may operate in one country, hold reserves through institutions in another and serve customers around the world. Different national standards can create complicated compliance obligations and leave gaps in supervision. The Financial Stability Board and other international bodies continue to examine these cross border issues, but their work does not replace domestic laws or supervisory decisions.
What Greater Clarity Could Mean for Bitcoin and Altcoins
Bitcoin does not depend on a stablecoin issuer or a central custodian to operate. Its network continues to process transactions through a decentralized system. Nevertheless, regulation can affect the businesses that connect Bitcoin to traditional finance, including exchanges, investment funds, brokers and custodians.
For Bitcoin, clearer institutional custody arrangements could make it easier for regulated firms to assess whether they can hold the asset on behalf of clients. More predictable reporting practices may also help financial institutions compare digital asset exposure with other investments. These developments could support participation over time, but they do not determine Bitcoin’s market price.
Altcoins may experience a more varied effect. Some projects rely heavily on centralized issuers, exchanges or reserve backed tokens. Others operate through decentralized networks with different governance and technical structures. A rule that helps one category of digital asset may impose additional costs or restrictions on another.
Stablecoins deserve particular attention because they are widely used as trading pairs, payment instruments and a way to move funds between platforms. If users and institutions gain greater confidence in reserve disclosures and redemption arrangements, stablecoins could become more dependable parts of the market’s financial infrastructure. Yet a stablecoin is not the same as a bank deposit, and its protections depend on the issuer, applicable law and the structure of its reserves.
Why a Stable Market Does Not Mean Risk Has Disappeared
Even if Bitcoin and major altcoins experience a calmer trading period, investors should avoid treating regulatory announcements as a direct signal to buy. Cryptocurrency markets remain sensitive to changes in global liquidity, central bank policy, leveraged positions, security incidents and sudden shifts in investor confidence.
Regulatory implementation can also create uncertainty before it resolves it. Companies may need to update internal controls, renegotiate custody arrangements, change reserve management practices or stop offering products that do not meet new requirements. These adjustments can carry financial and operational costs. Smaller providers may find compliance more difficult than large institutions with established legal and risk departments.
Investors evaluating a digital asset should therefore look beyond the headline. Useful questions include whether the issuer or service provider is properly authorized, how customer assets are held, whether reserve information is independently reviewed and what rights customers have if withdrawals are delayed. For volatile tokens, investors should also consider liquidity, concentration and the possibility of substantial losses.
What to Watch in the Months Ahead
The next stage will be less about announcements and more about implementation. Market participants will be watching the January 2027 effective date for the OCC stablecoin rule, further Federal Reserve rulemaking and how financial institutions adapt their custody and reserve procedures.
Internationally, differences between national frameworks will remain a key issue. Regulators will need to balance consumer protection and financial stability with the practical needs of payment providers, exchanges and institutional investors. The quality of supervision will matter just as much as the wording of the rules.
For cryptocurrency markets, regulatory clarity is best understood as infrastructure rather than a price guarantee. Better defined responsibilities and stronger reserve standards may help institutions participate with greater confidence. They may also expose weak business models and push some providers out of regulated markets. Both outcomes can shape the industry.
The reported stabilization of Bitcoin and major altcoins on October 31 may reflect improving sentiment around the direction of regulation, but the evidence supports a measured conclusion rather than claims of a confirmed global turning point. The important development is that governments are moving from broad policy discussions toward more detailed requirements for stablecoin reserves and digital asset custody. Whether that progress produces lasting market confidence will depend on effective implementation, transparent institutions and continued investor caution.