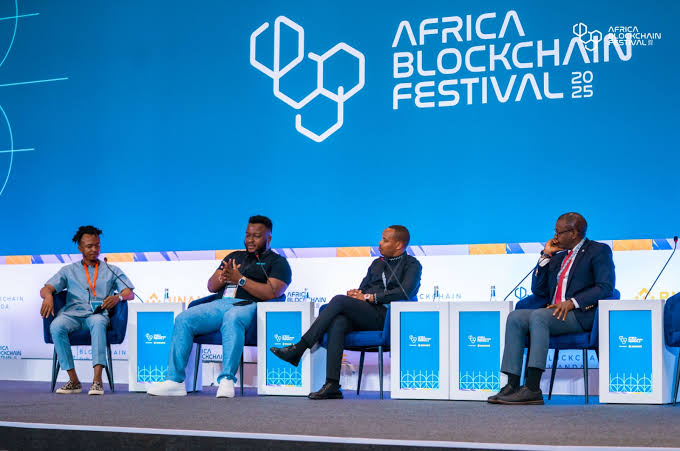
Blockchain technology is moving beyond cryptocurrency trading and into practical questions about how businesses operate, how financial services reach underserved communities, and how economic systems can become more transparent. At the Blockchain Africa Conference on October 15, 2026, industry leaders and developers gathered to examine how Web3 technologies could serve emerging markets through institutional adoption, asset tokenization, and real world blockchain applications. The discussions placed a central question before the industry: how can blockchain deliver measurable benefits for people and businesses facing everyday economic challenges?
Why Practical Blockchain Adoption Matters in Africa
Africa has become an important setting for conversations about digital finance because many communities and businesses face barriers involving access to banking, costly payments, limited financial infrastructure, and cross border commerce. Blockchain based systems may offer new ways to address some of these challenges, provided that solutions are affordable, reliable, legally compliant, and designed around the needs of local users.
The conference discussion reflected a broader shift in the blockchain sector. For years, public attention often centered on cryptocurrency prices, speculative trading, and new digital tokens. Those subjects remain part of the industry, but institutions, developers, and entrepreneurs are increasingly examining whether distributed ledger technology can improve existing services or support entirely new business models.
For a small business owner, the value of technology is not measured by technical complexity. It is measured by whether a supplier can be paid more efficiently, whether records can be verified without unnecessary delays, and whether financial services become easier to access. These practical considerations are particularly relevant in developing economies, where the cost of a transaction or a delay in receiving funds can affect a business’s ability to operate.
However, Africa is not a single market. Each country has its own financial regulations, banking infrastructure, mobile payment habits, and levels of digital access. A blockchain service that works in one location may require substantial changes before it can succeed elsewhere. Any credible assessment of Web3 adoption must account for these differences rather than treating the continent as one uniform market.
Institutional Adoption Moves Beyond Experimentation
Institutional adoption was among the central themes of the conference. Banks, financial service providers, payment companies, businesses, and public institutions are evaluating how blockchain networks might fit into their existing operations. Their interest is driven less by the novelty of the technology than by potential improvements in record keeping, settlement, verification, and the movement of digital assets.
For financial institutions, blockchain can provide a shared record of transactions that authorized participants can verify. Depending on the network design, this can reduce reconciliation work between organizations and make certain processes easier to audit. Institutions may also explore programmable transactions, in which predefined conditions govern when a transfer or another action takes place.
These possibilities do not mean that blockchain automatically makes financial services faster or cheaper. A network still requires secure software, dependable access, effective governance, and clear procedures for correcting errors. Institutions must also consider how blockchain records interact with existing databases, customer verification systems, privacy obligations, and national financial laws.
What institutions need before adopting blockchain
Successful implementation depends on more than a working technical demonstration. Institutions need a convincing business case, clear accountability, and evidence that a proposed system performs better than the alternatives. Important considerations include:
- Security controls that protect digital assets, user accounts, and sensitive information.
- Compliance procedures for customer identification, financial crime prevention, and applicable reporting obligations.
- Reliable integration with existing payment systems, accounting software, and business records.
- Transparent governance that explains who can make changes, resolve disputes, and respond to technical failures.
- Measurable evidence of lower costs, faster processing, improved access, or more dependable records.
These requirements help explain why institutional adoption often progresses gradually. A pilot project may demonstrate that a system works under controlled conditions, but a production service must also withstand operational disruptions, changing regulations, and the demands of real customers.
Asset Tokenization Opens New Questions About Ownership
Another major subject was tokenization, the process of representing rights to an asset through a digital token recorded on a blockchain or another digital ledger. Depending on the legal structure, a token may represent a financial instrument, a claim on an asset, a share of ownership, or a contractual right. The exact meaning matters because a digital representation does not automatically establish legal ownership.
For emerging markets, tokenization could create new ways to record and transfer certain interests in property, business financing, commodities, and other assets. It may also allow eligible investors to participate in investments that traditionally required substantial capital. Dividing an investment into smaller digital units could broaden access, although legal restrictions and minimum investment requirements may still apply.
Consider a business seeking funding to expand its operations. A properly structured tokenized investment could allow several eligible investors to contribute capital under defined terms. Digital records might simplify the tracking of ownership and certain transactions. Yet the business would still need enforceable agreements, accurate asset valuations, investor protections, and a lawful process for distributing returns.
Property related tokenization presents similar opportunities and limitations. A blockchain record may help organize information about ownership interests, but it cannot independently resolve disputed land titles, replace a country’s property registry, or guarantee that the person issuing a token has the legal authority to do so. Effective implementation requires cooperation between technology providers, lawyers, financial institutions, and public authorities.
Investors must also consider liquidity. A token can be easy to transfer technically while remaining difficult to sell in practice. If there are few buyers, unclear resale rules, or restrictions on eligible investors, the asset may not provide the flexibility its promoters suggest. Clear disclosures and enforceable rights remain essential to protecting participants.
Real World Use Cases Could Deliver More Lasting Value
The conference’s focus on practical blockchain applications reflects a growing recognition that lasting adoption depends on solving specific problems. Rather than beginning with a token or a particular network, developers and businesses need to identify the operational difficulty they want to address and determine whether blockchain is the most suitable tool.
Payments and cross border transfers
International payments can involve several intermediaries, separate processing systems, currency conversion costs, and delays in confirming that funds have arrived. Blockchain based payment arrangements may help some providers coordinate transactions or transfer digital value across networks. Their usefulness depends on local payment rules, currency access, settlement arrangements, and the availability of reliable ways to convert digital assets into national currencies.
Consumers and small businesses also need protection from fraud, sudden price changes, and unexpected fees. A payment system is not genuinely accessible if customers cannot understand its charges or recover from mistakes. For many users, a familiar mobile interface and dependable customer support may matter more than the technology operating behind the service.
Supply chains and product verification
Businesses that move goods through several suppliers can face difficulties confirming where products originated, when they changed hands, and whether supporting documents are accurate. A shared ledger can help authorized participants maintain a consistent record of recorded events. This may be useful in agriculture, manufacturing, logistics, and trade.
Still, a blockchain cannot guarantee that information entered into the system is true. If a supplier submits inaccurate information about a product, recording that information permanently does not make it accurate. Reliable verification procedures, physical inspections where appropriate, and clear responsibility for data quality remain necessary.
Digital identity and access to services
Digital identity systems may help people prove specific facts about themselves when accessing financial or public services. Blockchain related approaches could support verifiable credentials, allowing organizations to check information without maintaining every underlying record in one shared database.
Privacy must remain a priority. Personal identity information should not be placed on a permanent public ledger without careful consideration of the risks. Well designed systems can use controlled access and cryptographic verification to limit unnecessary disclosure, but implementation choices determine whether those protections work in practice.
Trade finance and business records
Small exporters and suppliers often depend on documentation to demonstrate that goods have been shipped, received, or paid for. Shared digital records could reduce certain reconciliation tasks and help counterparties verify transaction stages. The potential benefit is especially relevant where businesses work with several banks, logistics providers, and commercial partners.
However, blockchain adoption will not eliminate the need for trusted institutions, contract enforcement, or accurate commercial records. The strongest applications are likely to be those that connect digital verification with established business processes instead of attempting to replace every existing system.
Regulation and Consumer Protection Remain Essential
As Web3 services expand, regulators face the challenge of supporting useful innovation while limiting financial crime, misleading investment claims, market manipulation, and risks to consumers. The policy question is not simply whether blockchain should be permitted. It is how different applications should be governed according to the services they provide and the risks they create.
A token used to represent an investment may require different safeguards from a system that verifies shipping records. A service that holds customer funds may face obligations that do not apply to software that merely records information. Clear legal definitions can help responsible businesses plan their operations while giving customers a better understanding of their rights.
International cooperation also matters because digital assets and blockchain networks can operate across national boundaries. Guidance from organizations such as the Financial Stability Board provides an important reference point for discussions about financial stability and the oversight of crypto asset activities. Individual countries must still develop and enforce rules suited to their legal systems and financial conditions.
For consumers, basic safeguards include clear information about fees, realistic descriptions of risks, secure account recovery, accessible complaint procedures, and honest explanations of whether assets are protected by any deposit or investor compensation scheme. Users should be cautious of projects promising guaranteed returns, effortless profits, or risk free access to digital investments.
Skills, Infrastructure, and Local Participation Will Shape Growth
Technology alone cannot create a sustainable Web3 economy. Adoption depends on reliable internet access, affordable devices, digital literacy, technical training, and the availability of people who can build and maintain secure applications. Developers also need opportunities to work with businesses that understand local problems and can test whether proposed solutions deliver meaningful results.
Conferences can contribute by bringing developers into contact with financial institutions, entrepreneurs, investors, researchers, and public officials. These conversations are useful when they lead to practical collaboration, shared technical knowledge, responsible pilot projects, and opportunities for local talent to participate in the development of new services.
Local context should guide product design. An application intended for a small agricultural business, for example, may need to function on lower cost smartphones, support familiar languages, and provide a straightforward way to correct mistakes. A sophisticated platform that requires expensive equipment or extensive technical knowledge may struggle to reach the people it is intended to serve.
Education is equally important. Users need to understand private keys, account security, transaction fees, and the consequences of sending digital assets to an incorrect address. Businesses need training in cybersecurity, data management, and regulatory compliance. Without these foundations, new systems can introduce risks that outweigh their potential benefits.
Measuring Success Beyond Conference Announcements
The significance of the Blockchain Africa Conference will ultimately depend on what follows the discussions. Announcements and demonstrations can attract attention, but real adoption requires evidence that a service solves a genuine problem and continues to work outside a controlled environment.
Businesses evaluating blockchain projects should track practical measures such as transaction costs, processing time, error rates, system availability, user retention, and the number of successful transactions. They should also examine the costs of maintenance, security, compliance, and customer support. These measures provide a clearer picture of value than the number of tokens issued or the size of a project’s online following.
For institutions, carefully designed pilot programs can reveal whether blockchain offers an advantage over conventional databases or existing payment infrastructure. For regulators, transparent reporting and structured consultation can help identify risks before a service reaches a large audience. For developers, feedback from real users can expose problems that technical testing alone may overlook.
The most credible projects will be those that acknowledge limitations, protect users, and publish evidence of their results. Some applications may prove valuable, while others may be better served by simpler technologies. That distinction is a sign of a maturing industry rather than a failure of innovation.
A Practical Future for Web3 in Emerging Markets
The October 15 conference placed institutional adoption, tokenization, and real world applications at the center of the Web3 conversation. These themes reflect a broader effort to move beyond speculation and determine where blockchain can support more dependable financial services, transparent records, and useful digital infrastructure.
For emerging markets, the opportunity is meaningful but not automatic. New systems must fit local regulations, respect consumer rights, and work within the economic realities of the people expected to use them. Technology providers must demonstrate that their services are secure, affordable, and more effective than available alternatives.
Our assessment is that the most promising path forward lies in practical partnerships between local businesses, developers, financial institutions, and policymakers. Progress will not be measured by how quickly every organization adopts blockchain. It will be measured by whether carefully chosen applications reduce unnecessary costs, improve access, strengthen trust, and create lasting economic value.
As the industry continues to mature, the central challenge remains clear: turn technical potential into reliable services that solve real problems. For Africa and other developing economies, that is the standard by which the next phase of Web3 adoption should be judged.