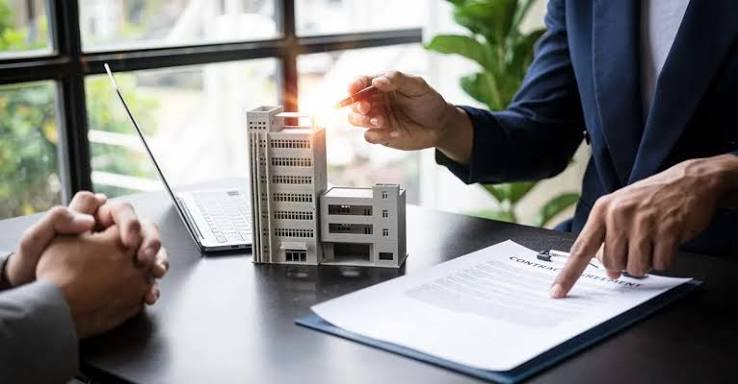
Commercial property markets across major global cities are entering another period of careful repricing as borrowing costs, bond yields and central bank expectations reshape investment decisions. From the United States and Europe to Japan, investors are weighing whether higher financing costs represent a temporary obstacle or a longer shift in the economics of offices, warehouses, retail centers, factories and other income producing assets. The developments unfolding around October 6 and 7, 2026 show why commercial real estate is increasingly being judged through the wider lens of monetary policy, industrial activity and global capital flows.
Interest Rates Are Once Again at the Center of Property Decisions
Commercial real estate depends heavily on financing. A building may generate reliable rental income for years, but the value of that income changes when the cost of borrowing changes. Higher interest rates can raise mortgage payments, increase refinancing expenses and reduce the price buyers are willing to pay for an asset.
That relationship is particularly visible in the United States. The Federal Reserve raised its benchmark interest rate by 25 basis points at its September meeting, taking the federal funds target range to 3.75 percent to 4.00 percent. Officials have since offered differing views about whether another increase will be necessary, leaving investors focused on upcoming inflation and employment data. The Federal Reserve has scheduled the release of its September meeting minutes for October 7 and its next policy meeting for October 27 and 28. :contentReference[oaicite:0]{index=0}
For property investors, the debate matters even when a building is performing well. A higher risk free rate can push investors to demand stronger returns from commercial properties. That can place downward pressure on valuations, particularly for assets that require substantial refinancing or have leases that are slow to adjust.
Bond Yields Are Adding Another Layer of Pressure
The commercial property story cannot be separated from the global bond market. Ten year government bond yields have climbed sharply across several major economies, increasing the return available from relatively low risk assets. When government bonds offer higher yields, commercial real estate must provide enough additional income to justify its greater exposure to vacancies, maintenance expenses, tenant risk and changing property values.
In the United States, the ten year Treasury yield stood above 5 percent in early October. That level has significant implications for property financing because lenders and investors use government bond yields as an important reference point when assessing commercial loans and required investment returns.
We are also seeing evidence that the impact reaches beyond the United States. Research published by De Nederlandsche Bank on October 6 found that changes in US monetary policy can generate meaningful spillovers into commercial real estate markets outside the country. The research points to international investment and credit channels through which American monetary conditions can influence property prices abroad.
Europe Faces a Complicated Mix of Growth and Inflation
European commercial real estate is dealing with an unusually mixed economic picture. Manufacturing activity has shown signs of improvement in several areas, yet higher energy costs and financing expenses remain significant concerns for businesses and property owners.
The European Central Bank raised its three key interest rates by 25 basis points in September, with the deposit facility reaching 2.50 percent. The central bank said inflation was expected to remain above its 2 percent target for an extended period and projected average headline inflation of 3 percent for 2026. The ECB also stressed that future decisions would remain dependent on incoming economic and financial data. :contentReference[oaicite:1]{index=1}
At first glance, the European manufacturing picture is less negative than the phrase factory slowdown might suggest. Eurozone factory activity actually accelerated in September, with the manufacturing purchasing managers index reaching its strongest level in more than four years. Demand for investment goods, defense equipment and technology related capital goods provided support.
Germany, however, illustrates why investors remain cautious. German factory orders fell sharply in August, while high energy costs continued to weigh on energy intensive industries. Industrial production later rebounded strongly in August, demonstrating that the region is not moving in a simple straight line. For commercial property investors, that unevenness matters because warehouses, factories, logistics facilities and office buildings depend on the strength of the companies occupying them.
Japan Adds Another Dimension to the Global Property Picture
Japan has become increasingly important to international investors because its monetary policy is moving through a different phase from the ultra low rate environment that shaped global capital markets for years.
The Bank of Japan is currently guiding its overnight call rate at around 1.25 percent. Its September policy meeting produced updated guidance, while the next monetary policy meeting is scheduled for October 29 and 30. That makes Japanese rate expectations another important factor for global investors considering currency exposure, financing costs and international property allocations.
For Japanese commercial property itself, higher rates can affect borrowing and capitalization assumptions. For overseas markets, the effects can also travel through investment flows. Japanese institutions have long participated in international markets, and changes in domestic yields can influence how attractive foreign real estate looks after currency and financing costs are considered.
Office, Industrial and Retail Properties Will Not React the Same Way
One of the biggest mistakes in discussing commercial real estate is treating every property type as though it responds identically to interest rates. The current environment is creating different opportunities and pressures across sectors.
Office Property
Office buildings remain particularly sensitive to refinancing conditions because many properties purchased during periods of inexpensive debt now face higher financing costs. Owners may need to invest more capital in renovations, amenities and energy efficiency while also competing for tenants with changing workplace requirements.
Buildings with strong locations, modern infrastructure and reliable tenants can remain attractive. Older properties with high operating expenses and significant vacancy may face much greater valuation pressure. Investors are therefore paying closer attention to building quality and tenant strength rather than relying only on broad market recovery expectations.
Industrial and Logistics Property
Warehouses and logistics facilities have benefited from long term changes in supply chains, online commerce and domestic manufacturing. However, these assets are not immune to higher interest rates. Construction costs, land prices and financing expenses can make new development more difficult, potentially supporting existing properties when demand remains healthy.
Manufacturing activity is also becoming an important consideration. A factory slowdown can weaken demand for industrial space in one market while government investment, reshoring and technology spending can increase demand in another.
Retail Property
Retail property is closely tied to household purchasing power. Higher borrowing costs can affect consumers through mortgages, credit expenses and general financial conditions. At the same time, stronger employment and wage growth can provide support.
This creates a highly selective market. Well located shopping centers with strong tenants may continue attracting investors, while weaker properties can struggle if consumer demand softens and refinancing becomes more expensive.
Global Investors Are Becoming More Selective
The changing monetary environment is encouraging investors to look beyond headline property prices. Cash flow quality, debt maturity, tenant concentration, lease structure and local economic growth are becoming increasingly important in investment decisions.
A property that appears inexpensive may not actually be cheap if it requires a large refinancing package at substantially higher rates. Conversely, an expensive property with long leases, strong tenants and limited near term debt requirements may provide greater stability.
This is why commercial real estate investment decisions are increasingly centered on the relationship between property income and financing costs. Investors are asking how much rent can grow, how long tenants are likely to remain, what capital improvements will be required and what happens when existing loans mature.
What the Monetary Shift Means for Property Buyers
For institutional investors, the current environment may create opportunities as sellers become more realistic about pricing. Owners facing refinancing pressure can become more willing to negotiate, particularly when a property has experienced higher vacancies or weaker income.
For smaller investors and businesses, however, the challenge is different. Higher financing costs can reduce purchasing power even when property prices begin to decline. A lower purchase price does not automatically mean a lower monthly financial burden if the interest rate attached to the transaction is substantially higher.
We believe this distinction will remain central to commercial property decisions through the remainder of 2026. The most attractive opportunities are unlikely to be determined by price alone. They will depend on whether the underlying property can produce dependable income through different economic conditions.
Why the Next Few Months Matter
Commercial real estate investors now have several major variables to watch at the same time. US inflation and employment figures will influence expectations for Federal Reserve policy. European inflation and industrial data will shape expectations for the ECB. Japan will remain under scrutiny as investors assess the Bank of Japan’s next moves. Meanwhile, bond yields, energy prices and currency movements can alter property financing conditions even without an immediate change in central bank policy.
The result is a market that rewards patience. Property owners with manageable debt and strong tenants have more room to wait. Buyers with available capital can examine assets that may have been too expensive during periods of abundant cheap financing. Developers, meanwhile, must be more disciplined about construction costs, expected rents and the timing of debt funding.
A More Selective Era for Commercial Property
The global commercial real estate market is not simply moving from boom to bust. It is undergoing a more complicated adjustment in which money has become more expensive, economic growth is uneven and central banks are no longer moving in lockstep.
For investors, that means the quality of the asset matters more than ever. Prime locations, dependable tenants, efficient buildings and sustainable cash flows can provide resilience when financing conditions become difficult. Properties dependent on rapid rent increases or inexpensive refinancing face a much harder test.
As October progresses, the central question for global commercial real estate will not be whether interest rates rise or fall at a particular meeting. The bigger question will be how long borrowing costs remain elevated and how businesses, lenders and investors adapt to that reality. From New York and London to Frankfurt and Tokyo, the answer will shape property prices, development plans and investment flows well beyond the next central bank decision.